Not quite. Try again.
Rebuilt on your direction · September 1
And one door closes sooner than anyone told you
Until the Publix Sports Nutrition appointment form is due
Twenty-four accounts, five channels, every door dated or honestly marked unknown.
Built to be forwarded. Section 08 is written for Pietro.
01 · What you asked for
This morning you told us where the traction is and where it is not. We took it literally and rebuilt it the same day. The version you clicked through on the call is still here, linked at the bottom of this page and in the menu. This is what it became.
“The part that’s really interesting to me is this retail, the buying committee, and having support there. That’s where I need the most help, because that’s where we’re going to get the most traction.”Mirek · 1 September
“What are the ten, fifteen, twenty retail accounts, both regional and national, that we should go after? The timeline of what was needed by when.”Mirek · 1 September
“Before you have velocity, you need awareness. I wonder if velocity is putting the cart before the horse.”Mirek · 1 September
Removed, not repriced
You were direct about it and you were right, so we are not going to negotiate you back toward it.
“There’s no way I can do that. This is more money than I give the talents themselves. The talent is just getting product. And frankly the team’s not big enough.”Mirek · 1 September
You have signed five cycling and running teams in a fortnight on product alone. That programme works because it costs you product, and a management layer priced above the athletes would have broken the logic of it. It comes back when there is a paid channel to point it at, and not before. Everything below assumes you keep running ambassadors yourself.
What is different in this version
01
Retail and the buying committee. The end-user work survives only where it feeds a buyer conversation, which is section 02.
02
Sprouts was the worked example. It was never meant to be the list. Section 03 is the list, across five channels including the one you asked about.
03
Where a retailer publishes a window we cite it. Where they publish nothing the row says so and the cell stays empty. Five of the twenty-four are in that state.
04
You said you would take this to Pietro. Section 08 is written for someone who was not on the call.
02 · Awareness earns the velocity
We led with velocity because velocity is what a buyer asks for. You pointed out the obvious thing we had skipped, which is that velocity is an outcome and awareness is what produces it. That is not a wording change. It changes what gets built first.
First
Not a national campaign. Demand created inside the trade areas of the doors you already have or are about to win, so it shows up in a number a buyer can see. A shopper in Walnut Creek matters to the Sprouts category manager. A shopper in Ohio does not, yet.
Then
Units per store per week, repeat rate, basket incrementality. Sixteen Sports Basement doors are producing this right now and nobody is capturing it. That instrumentation is the first thing we would build, and we will build it whether or not you hire us.
Then
A category manager who can present a real velocity read is presenting evidence. One who has a deck is presenting an opinion. The whole of section 05 exists to move you from the second to the first.
The honest constraint
Your online exclusivity with The Feed covers the sports nutrition line. The bars appear to sit outside it, and that is the single most useful thing said on the call. Without some measurable path from a recommendation to a purchase, awareness spend cannot be proved and every conversation about scaling it becomes an argument about taste. We would like fifteen minutes on what the contract actually says before we design around it.
03 · The retail map
You asked for the ten, fifteen or twenty accounts and the timeline of what is needed by when. Here are twenty-four, across twenty-seven doors, because three of them have more than one way in. Where a retailer publishes a window the date is here, with the source in the footer. Where a retailer publishes nothing the row says so. Five of them publish nothing, and knowing which five is worth as much as the dates, because it tells your reps which accounts need a relationship rather than a filing.
04 · Two doors are open right now
You mentioned a Publix meeting coming up. Publix is the only retailer on the whole list that publishes an actual dated schedule, and the row that matters has a gate in front of it that most brands find out about after it has shut.
Publix · Sports Nutrition · RSS 25
2
days until the form is due
The review opens 18 September. Publix requires the Appointment Request Form at least two weeks before the review start date, which puts it at roughly 4 September. Miss the form and the review happens without you, whatever meeting is already in the calendar.
Sprouts · two departments, not one
30 Nov
Vitamins Fitness submission closes
Grocery Nutrition Bars opened on a rolling basis on 15 June and has no end date. Vitamins Fitness, which contains sports nutrition, closes 30 November and resets 31 December. Two departments, two category managers, two shelf sets. Run both.
Worth knowing about the Sprouts date
Sprouts' own calendar page renders that Fitness row as “Open” because of how the page is coded. The 30 November date is real and published by Sprouts, but it only appears in the data file behind the page. Anyone who checks the calendar page will conclude the date is invented. The file is cited in the footer. Use that link, not the page, if this ever gets questioned internally.
05 · How we work a buying committee
You asked how this scales past Sprouts, and how much of it is automated. Honest answer: the research is part automated and part done by analysts, and the reason we do not fully automate it is that the roles below are named differently at every retailer and getting the name wrong wastes the campaign. What does scale is the shape. Five seats, five different reasons to say no, five different pieces of paper.
We run this against two hundred accounts for other clients. Twenty-four is not a stretch.
Two of these five are documented by the retailers themselves. Natural Grocers publishes that a New Items Approval Committee meets monthly and that review takes up to ninety days. Publix schedules a New Item Meeting inside every cycle and names a category manager and a contact against each category. The rest of the shape is drawn from how these accounts actually behave, and we would refine it with your reps before asserting any of it at you.
06 · Convenience, and other doors
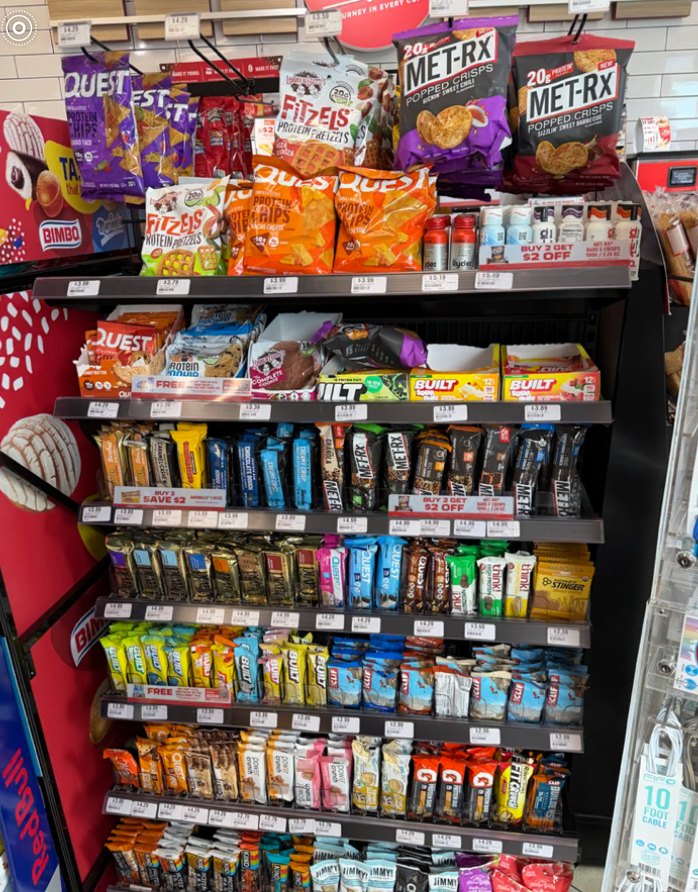
Chevron · Meridian Avenue · San Jose
The photograph from the last version. You asked the right question about it.
There is no Chevron buyer to present to. ExtraMile is a joint venture between Chevron and Jacksons Food Stores, and its eleven hundred locations are run by Chevron, by Jacksons and by independent franchisees. The banner sets a planogram, and the franchisee orders from whichever wholesaler serves them.
Which means the route into that shelf is the wholesaler, and one of them publishes its price list.
McLane Emerging Brands
A dropship marketplace built to route new brands to convenience retailers, reaching forty thousand plus of them. Published cost: $500 setup, 12.5% commission, $450 a year. Catalogue data syncs to 1WorldSync, you ship a sample case for QA, and the product goes live fulfilled by dropship. No warehouse listing. No slotting negotiation. No corporate presentation.
That is the cheapest credible test of a whole channel that exists anywhere on this page, and it is the answer to the photograph. Core-Mark runs a comparable accelerator across roughly fifty thousand locations, though the only submission deadline they publish is from 2023, so we would call them before quoting you a date.
One caveat we will not paper over. We verified the ExtraMile ownership structure and we verified the wholesaler programmes, separately. That a bar reaches a Chevron shelf specifically through McLane or Core-Mark is our inference from those two facts, not a documented process. We would confirm it with a distributor rep before you spend anything.
Three more we can open, none of which are on a rate card
Talent, without a talent budget
We are partners with them. College NIL money concentrates on a handful of quarterbacks, and underneath that sits a deep bench of Hispanic athletes with real regional followings. You already sign college teams and athletes on product alone. This is the same motion, aimed at the Southwest markets where Del Toro already means something, at a price that makes it a test.
Specialty carriage
Twenty minutes from our office, and our team knows the founder personally. More independent US specialty dealers than any bike brand in the country, no nutrition line of its own, and its shops sell somebody else's gels to exactly the rider who should be buying yours. We still have not called. We wanted to ask you first.
A single high-intent site
One of our partners is close to the general manager of the Walton fitness facility in Bentonville, among the largest in the country. One site, a captive audience with the right habits, and a clean read on whether the bar sells to somebody who is not already a cyclist.
None of these reopens the budget line you cut. They are relationships, and what they cost is a phone call. They are here because you asked how any of this scales, and this is the part of the answer that does not come from a portal.
07 · Thirty, sixty, ninety
You asked what you could expect over thirty, sixty and ninety days, and said it needs to be concrete enough to take to Italy. Each block below ends with the thing that exists at the end of it, which is the part Pietro will read.
30
days · by 2 October
60
days · by 1 November
90
days · by 1 December
08 · Before the number, two things for Italy
You gave us the bar category from memory on the call, with the caveat that you were reconstructing it. We went and pulled the measured data, because anything that travels to Pietro should be sourced. Three of your four numbers move, and every one of them moves in your favour.
$7.5B, up 3%
$10.9B
Total snack and granola bars
up 7.1%
Circana, 52 weeks ending 22 March 2026. Prior year was $10.1B and up 1.9%, which is close to the figure you had.
~$3B protein
$5.9B
Nutritional bars
up 15.4%
The closest measured segment to what you described, and 54% of the category, which matches your half-the-category instinct exactly.
Quest owns the growth
+1.1%
Quest net sales
fiscal Q3 2026
Quest is the incumbent now, roughly flat. Barebells grew 142% to $483M and David went from nothing to about 16,000 doors in two years.
Clif has lost its way
Twice
Clif Builders Oreo launches
2025 and June 2026
Their innovation lead is on the record saying consumers want “indulgence and taste”. Eight years inside that business and you called it before we found the quote.
The correction that matters for strategy is the third one. If the high-protein low-sugar lane were compounding under Quest, a new entrant would be walking into a wall. It is not. The incumbent is flat and the growth is going to challengers who arrived in the last twenty-four months. That is a materially better story to take to Italy than the one you had, and it is sourced.
The lineup you described, as we understood it
Protein · segment one
The lane where the growth is and where the challengers are winning. Sweetener type is not the objection here.
Protein · segment two
The everyday bar, for the shopper who reads the sugar source rather than the sugar number.
Energy
Chocolate chip and cranberry. The closest comparison on shelf is Clif, which is currently busy becoming a cookie.
Energy
Soy crisp. Oatmeal, and one part-enrobed in chocolate. A texture position nobody in the set is holding.
Correct us on any of this. We built it from the call, and the SKU detail should come from your team before this goes anywhere.
08 · What it costs
The talent line is gone, so the menu is gone with it. What is left is the front you kept, at the price it already carried. You have the 26 August page in front of you, so here is the arithmetic rather than a new number.
The price did not move. The unit did.
You have the 26 August page, so here is the arithmetic rather than a new number. Front 02 was the buying committee at $4,250 a month, and the line under it read “Sprouts and Raley’s worked as named accounts”. Two. The end-user front was $4,750, the talent front $3,250, and all three together $9,750.
You cut two of the three fronts. We did not reprice the one you kept. What we have done instead is say plainly what a named account costs, because twenty-four of them is twelve times the work that $4,250 was quoted against, and pretending otherwise would be a promise we could not keep in month four.
So the map in section 03 is not the price. The map is yours either way, and it took us a day. What costs money is working an account: an analyst verifying the committee, a submission pack built to that retailer’s own field list, a live campaign against the named seats, and a coverage ratio reported every week. Pick how many of those you want running.
Where you already were
$4,250
per month · no term
The published Front 02, unchanged. Sprouts and one more worked properly, plus the Sports Basement velocity instrumentation. Start here if you want to watch the work before you widen it.
What we would recommend
$6,750
per month · no term
Sprouts, Publix, one more of the natural channel and the convenience route. Four is the smallest number that covers the doors with real dates on them and still leaves one to move as your reps open something.
The full natural-channel push
$9,750
per month · no term
The number you already have from the 26 August page, now buying six accounts worked to depth instead of three fronts worked thinly. Right once the first velocity read is in hand and you are widening on evidence.
Above six we quote it, because at that point it is a different staffing conversation and we would rather price it honestly than discover the gap in month four. The twenty-four account map in section 03 is not a delivery number. It cost us a day, it is yours at any tier and at none, and it exists so that the accounts we do work are the right four.
What one named account buys, every month
01
An analyst names the seats and confirms them. Not a list scraped from a database and handed to you unchecked.
02
Built to that retailer’s own field list and filed inside its window, or the window documented if there is not one.
03
Running against the named seats, with the creative and the point-of-view asset produced by us.
04
Reported weekly. Four of nine seats reached, moving to seven of nine. The number you asked for on the call.
Three things we want to be unambiguous about
Media is not in any of these numbers. Programmatic against a buying committee is cheap, but it is real money and it stays yours, visible, in your own accounts. Nothing passes through us with a margin on it. The map is yours either way, at any tier and at none, because we built it before you agreed to anything. And accounts can move month to month. If Publix goes quiet and Whole Foods opens up, we swap them, without a change order.
We want to be your North America arm, and we would rather earn that than be granted it. The three things marked no fee above are already underway. They are yours whichever way this goes.
The nearest door closes this week →